US


Salary is only about two thirds of what a billable employee costs. Payroll taxes, benefits and overhead make up the rest.
Fully loaded, a billable employee costs closer to 1.4 to 1.5 times base salary, not the 1.25 times most firms round to.
The cost on its own decides nothing. What matters is whether utilization and bill rate cover it together.
Billable utilization across professional services fell to 66.4% in 2025, the lowest SPI Research has recorded and well short of the 75% most firms plan around.
A $95,000 consultant at 70% utilization breaks even at $102 an hour, and needs about $340 an hour to protect a 70% delivery margin.
When the math does not work, you have four levers: raise the bill rate, improve utilization, redistribute non-billable work and, last of all, reconsider headcount.
The starting convention, cited by the Small Business Administration and echoed across most HR and payroll guidance, is that an employee’s fully loaded cost runs 1.25 to 1.4 times their base salary. In other words, a $95,000 hire costs somewhere between $118,750 and $133,000 once you add taxes, benefits, and basic overhead.
That range is a reasonable starting point for a generic hire. It's the wrong starting point for a billable role because it doesn't address the question that determines profitability: how many of that person's hours you can sell, and at what rate. A $95,000 marketing coordinator and a $95,000 billable consultant can have identical fully loaded costs and completely different economics because only one has a bill rate attached to their time.
Every employee cost calculator on the first page of Google treats "employee" as one undifferentiated category. None ask whether the person is billable, and that's the gap worth exploiting, because it's the only variable that determines whether you recover their cost.
A non-billable employee’s cost is a fixed number you absorb through overall firm margin. You have to recover a billable employee’s cost through a rate multiplied by hours actually sold before it contributes anything at all. That changes what "true cost" needs to answer. It’s not just "what do they cost me." It’s "what rate, at what utilization, breaks even on that cost, and what’s left over after it does."
Nobody currently answers that second question. This article does.
Start with salary, then add mandatory employer taxes. Employers match 6.2% for Social Security (on wages up to the 2026 wage base of $184,500) and 1.45% for Medicare, with no cap. That’s 7.65% added to base pay before anything else gets counted, and it’s non-negotiable regardless of firm size or industry.
Nationally, benefits now make up 31.6% of total civilian compensation, according to the latest Bureau of Labor Statistics data. That figure spans every industry and wage level, so treat it as a ceiling rather than a rule for any single role. For a mid-size professional services firm offering standard health coverage, retirement matching, and PTO, a benefits load of roughly 20-25% of salary is a more realistic planning figure, with tools, software licenses, and workspace overhead adding another 10-15%.
This is the piece every calculator either skips or badly underestimates. According to SHRM, the total cost to hire and ramp a replacement can run 3 to 4 times the position’s salary once you count lost productivity during the search, ramp-up time, and the output gap while a seat sits empty. That’s not an annual cost. It’s a risk-weighted one: the more likely a role is to turn over, the more that figure belongs in your planning math, even if it never shows up on a single invoice.
Here's where the calculators stop, and the real question starts. A fully loaded cost of $140,000 means nothing on its own. What matters is how many billable hours that person actually delivers, because every hour they don't bill is a fixed cost with no offsetting revenue.
Across the industry, this is getting worse. Billable utilization across professional services firms fell to 66.4% in 2025, down from 68.9% the year before, according to the 2026 SPI Research Professional Services Maturity Benchmark — the lowest figure in the survey’s history, and well short of the 75% target most firms plan around. Firms hitting that target saw $210,000 in revenue per billable consultant in 2025, up 6% year over year. Firms below it didn’t. If you want the full breakdown by seniority and sector, we’ve mapped current benchmarks in detail.
A five-point utilization gap sounds small until you run it through the cost math. On that same $140,000 fully loaded consultant, dropping from 75% to 66% utilization doesn’t just mean "a bit less billed time." It means roughly 175 fewer billable hours a year at the same cost. Resource management tooling exists specifically to catch that gap before it shows up in a quarterly margin review instead of a weekly capacity report.

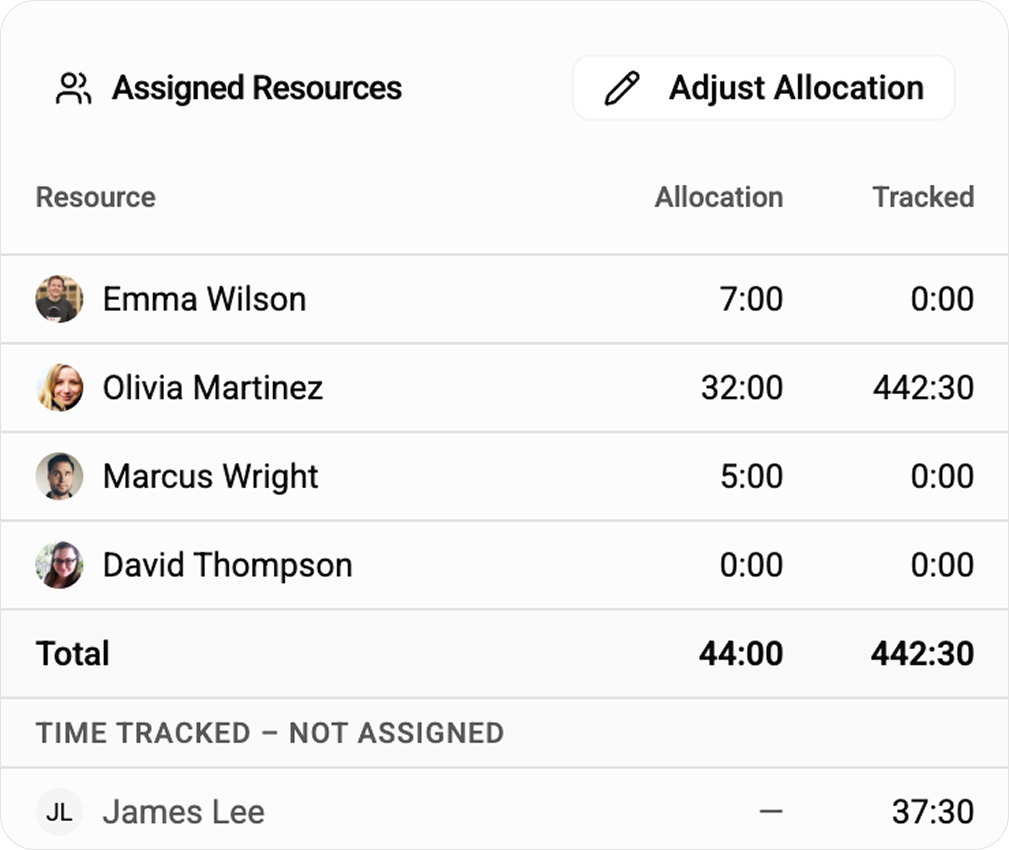
Compare planned hours with the hours your team logged
Free for 14 days · No credit card required
Once you know fully loaded cost and realistic utilization, the break-even bill rate is simple arithmetic: divide the annual cost by the billable hours you can actually expect, not the hours in a calendar year.
Take a consultant earning $95,000 at a firm with standard benefits and moderate overhead:
Fully loaded annual cost: ~$140,268 — roughly 1.48x base salary, higher than the generic 1.25-1.4x convention because it accounts for overhead most calculators leave out entirely.
Assume 1,960 available working hours a year after PTO and holidays, at a realistic 70% utilization target. That’s 1,372 billable hours. Divide the fully loaded cost by that figure, and the break-even bill rate is $102 an hour. Using the standard delivery margin formula from agency rate-setting guidance — bill rate equals cost-per-hour divided by (1 minus your target delivery margin) - a firm targeting a healthy 70% delivery margin needs a bill rate closer to $340 an hour, not $102.
Now run the same math on a junior consultant earning $65,000. Fully loaded cost comes to roughly $95,973, and juniors typically run higher utilization (closer to 75%, since their time is more often billable execution work rather than client management). At 1,470 billable hours, the break-even rate is $65 an hour, and the margin-protecting rate at 70% delivery margin is $218 an hour.
That's the part firms miss. The junior's fully loaded cost is 32% lower than the senior's, but the margin-protecting rate only drops by about 36%, not in proportion to how much cheaper the junior "feels." Payroll tax and overhead percentages stay roughly constant across levels, so firms that price junior time as simply "cheap" without running this math often end up recovering less margin on junior work than they assume, not more.
That gap between "what covers cost" and "what actually protects margin" is the whole reason this math matters. A rate card that looks aggressive to a client-services lead is often just the number required to keep the lights on once you honestly account for utilization gaps, benefits, and overhead. Profitability dashboards that show this at the individual and project level, not just at the firm level, catch a rate quietly running below break-even before it erodes a quarter’s margin.
Run this math on your own team and one of two things happens. Either your current rates and utilization clear the bar, or they don’t. If they don’t, you have four options, and they are not interchangeable.
The direct fix, and the hardest to execute mid-engagement. It works best at renewal or for new business, where you can reset the number without the client feeling like the rules changed under them. Agencies that address margin at the rate level tend to recover fastest, but it depends entirely on what the market will bear for the work being done.
Often the more realistic lever, because it doesn't require a client conversation at all. Closing a five-point utilization gap can be worth more to margin than a modest rate increase, since it converts existing paid capacity into billed revenue rather than asking a client to pay more for the same thing. This is the lever resource management tooling is built to move.
Sometimes the cost problem isn't the person; it's what they're spending non-billable time on. Admin, internal meetings, and status reporting that could sit with operations or be automated should show up as billable time instead.
The last resort, and the one every other lever exists to avoid. If a role's realistic utilization and achievable rate genuinely can't clear its fully loaded cost after trying the first three levers, that's a structural problem, not a productivity one, and it needs a structural answer.
Most firms know what their people earn. Far fewer know what they cost once they honestly factor in utilization and overhead, and fewer still have checked whether their current rates actually clear that number. That gap between assumed cost and real cost is where margin quietly disappears. Run the math on one role this week using the formula above, and you'll know immediately which of the four levers you're actually working with. Track it weekly alongside your other core metrics, not just at the annual budget review.
Get Started with Magnetic
Start a free trial and see Magnetic with your own projects. No credit card required.
Fully loaded cost is salary plus payroll taxes, benefits, and overhead, all added together. Salary alone is only the starting figure, typically 65-70% of the real total.
Yes, the fully loaded cost calculation (salary, payroll taxes, benefits, overhead) applies to every employee, billable or not. The difference is what happens next: a non-billable role has no bill rate to measure against, so its cost gets absorbed through overall firm margin instead of recovered directly. Their value gets judged on effectiveness, not cost recovery.
At least once a year, since payroll tax caps, benefits costs, and salary bands all shift annually. Recalculate sooner if utilization drops meaningfully or a role's scope changes, since a stale cost figure can make a rate look profitable when it no longer is.
Most firms track cost in payroll or finance software and utilization in a separate time-tracking tool, which is exactly how the gap between them goes unnoticed. A resource management and reporting platform that connects the two shows fully loaded cost, utilization, and bill rate for the same person on one dashboard, rather than reconciling three sources by hand.
The core formula holds either way, but hourly employees carry more cost flexibility since pay scales with hours worked. Salaried employees carry a fixed cost regardless of hours worked, which is exactly why utilization matters more for them: the cost doesn't flex down in a slow month.
Payroll taxes and core benefits stay the same regardless of location. Overhead often shifts rather than disappears: less office cost, more spent on remote tooling, stipends, or coordination overhead, so the total doesn't necessarily drop as much as firms expect.
Jenna Green
Head of Growth
at Magnetic
Jenna Green leads marketing at Magnetic. She's worked across agencies, startups, and B2B SaaS, giving her first-hand experience of the operational challenges service firms face.

Magnetic is an all-in-one workflow management platform designed and built for professional services firms.